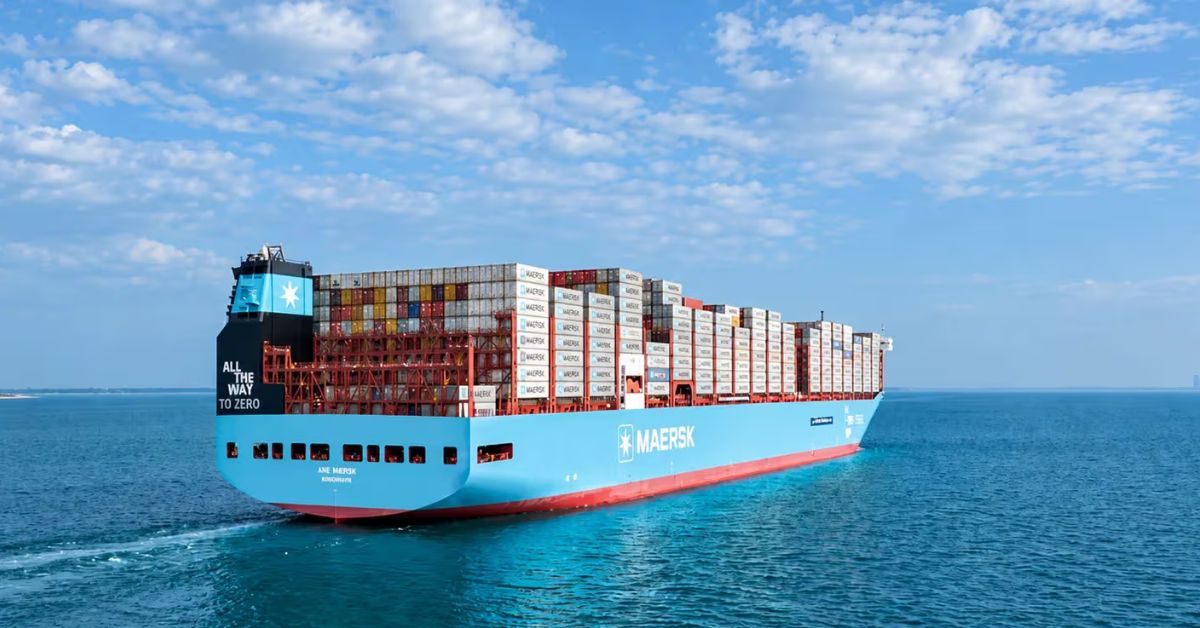
Maersk has surpassed COSCO as the largest operator in intra-Asian container traffic, the largest containerised trade in the world, according to the latest fleet count from Alphaliner as of mid-August.
How much capacity has Maersk deployed in the region?
The Danish shipping line had over 340,000 TEUs deployed in intra-Asian services after adding around 34,000 TEUs over the past year, the largest nominal increase of any operator in the market. Maersk closed the count with 343,021 TEUs, up from 308,635 TEUs twelve months earlier.
Why has Maersk’s position strengthened in this market?
Maersk’s leadership is partly attributed to the Gemini Cooperation’s radial hub-and-spoke model, which relies on a broader network of Asian shuttle services to feed its main east-west routes. Its 108 vessels in the region average 3,176 TEUs, the largest average vessel size among major intra-Asian operators.
How does COSCO’s position compare despite operating more vessels?
COSCO came in second place despite operating more than 120 vessels, as its deployed capacity barely changed year-on-year, rising only marginally from 314,668 TEUs to 315,162 TEUs.
How large is the overall intra-Asian container market?
Alphaliner estimates total deployed capacity in international intra-Asian services, excluding domestic traffic, at just under 2.6 million TEUs, up 6.2 percent year-on-year from 2,434,354 TEUs to 2,584,148 TEUs. This growth outpaced the global container ship fleet, which exceeds 34 million TEUs and grew by more than 5 percent over the same period. More than 80 shipping lines currently compete on the route.
How competitive is the market structure between major and regional lines?
The market remains one of the most fragmented in container transport, with small regional and feeder shipping lines accounting for 37 percent of deployed slots. Major line operators control over 63 percent of capacity despite operating fewer vessels, owing to an average vessel size of 2,699 TEUs, more than double the 1,338 TEU average among regional carriers.
Which other carriers saw notable changes in capacity?
CMA CGM recorded the second-largest capacity increase, adding 15,000 TEUs to overtake Evergreen for third place at 214,406 TEUs. Evergreen followed in fourth position with 205,593 TEUs, while MSC fell to 166,542 TEUs, a 2 percent decrease. SITC remained the leading regional specialist, operating 109 vessels and around 157,000 TEUs to place sixth, the only regional line with more than 100 active vessels in intra-Asian traffic, reflecting its strategy of connecting smaller, niche ports rather than competing purely on scale.
Which operators saw the sharpest gains or losses?
Among the top twenty operators, GSL recorded the highest relative growth, increasing 72 percent to 25,842 TEUs, followed by Samudera at 26 percent and Interasia at 20 percent. Conversely, TS Lines cut capacity by 25 percent to 30,444 TEUs, and Hapag-Lloyd reduced its presence by 22 percent to 25,046 TEUs. Sinokor decreased by 7 percent to 81,461 TEUs, while ONE and Yang Ming grew by 7 percent and 6 percent respectively, reaching 97,593 TEUs and 61,481 TEUs.
What is happening with intra-Asian freight rates?
The Drewry Intra-Asia Container Index rose 1 percent last week to $1,323 per FEU (forty-foot equivalent unit). The composite index has been trading at historical highs this month, a period marked by continued geopolitical disruption and typhoon-related supply chain interruptions limiting available capacity.
What does this mean for the intra-Asian shipping market going forward?
Maersk’s overtaking of COSCO reflects a broader consolidation of capacity around hub-and-spoke network strategies among major carriers, even as the intra-Asian trade remains structurally fragmented, with dozens of regional and niche operators continuing to compete alongside the largest global lines for share of the world’s biggest containerised trading lane.
 Join our WhatsApp channel for more updates:
 Subscribe to our YouTube channel for more updates: