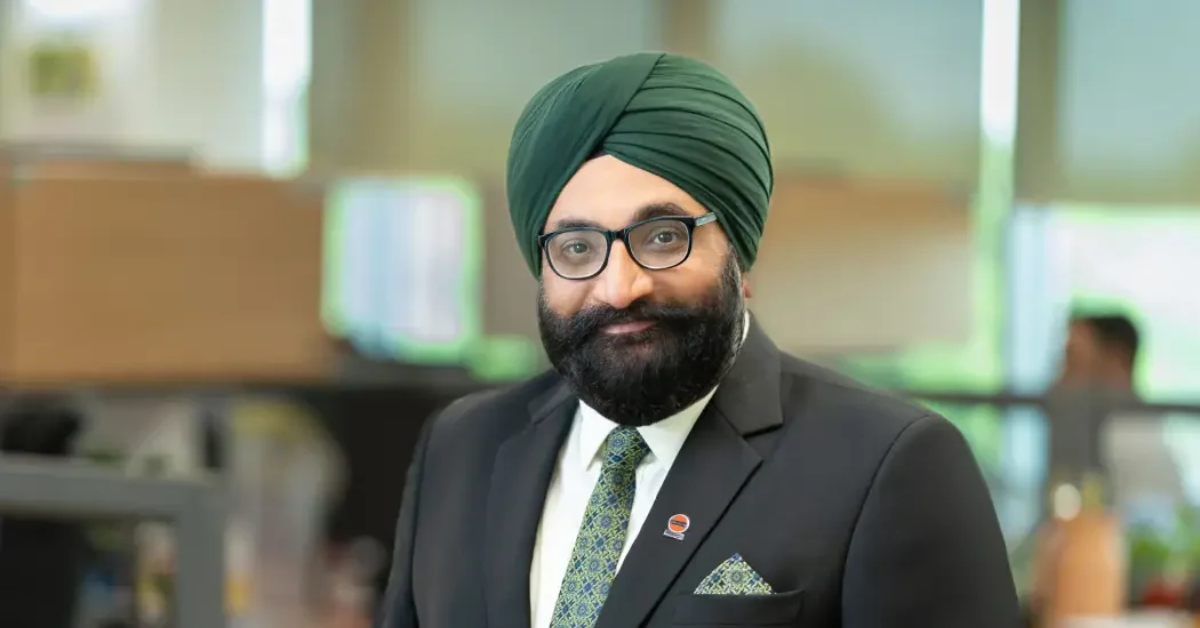
India needs to build up its own shipping capacity or watch freight costs consume the benefit of discounted crude purchases, Indian Oil Corporation chairman A S Sahney said, in a blunt admission that the country’s tanker fleet has not kept pace with its refining ambitions.
“We have been neglecting shipping… we have to build our capabilities in shipping. Today we are getting crude at a discount but freight is eating that up. Freight is a killing factor,” Sahney said on a panel at the Energy Technology and Innovation Meet in Goa on Tuesday.
His remarks put a number-free but unambiguous price on a structural weakness: India buys crude on favourable terms in a disrupted market, then pays much of that advantage back to shipowners in charter hire.
Why Freight Has Become the Decisive Variable
The timing of Sahney’s comment is not incidental. Freight rates for Russian oil exports from western ports to India hit record highs in early October, driven by heightened security risk in the Black Sea and a broad rally in tanker fees globally.
That combination — discounted crude available only at distant, higher-risk load ports — exposes the arithmetic Indian refiners run every day. A discount of a few dollars a barrel can be erased by a freight rate that has doubled. When war-risk premiums, longer voyages and constrained tonnage all stack up, the sourcing advantage narrows to the point where the refinery’s crude slate decision is effectively made by the tanker market rather than the trading desk.
The strategic consequence is that energy security and shipping capacity are now the same conversation. A country that imports 85–90% of its crude but owns a marginal share of the tonnage carrying it has limited control over its own landed cost — and no ability to insulate itself when charter markets spike.
The Fleet Gap in Numbers
India’s own fleet remains small relative to the volume it moves. Reported policy targets point to an unusual starting point: only about 5% of the crude tankers India uses are domestically built, with an aim to raise that to 7% by 2030 and substantially higher by 2047.
The government has been working on a programme reported at roughly $10 billion for 112 crude carriers through 2040 — a long-dated plan that reflects both the capital intensity of fleet building and the lead times at Indian yards.
| Fleet indicator | Position |
| Share of crude tankers domestically built | ~5% |
| Target by 2030 | ~7% |
| Reported fleet programme | ~$10 bn for 112 crude carriers to 2040 |
| Crude import dependence | 85–90% of requirement |
The commercial logic for owning tonnage is strongest precisely in stressed markets. Time-chartered foreign tonnage is priced at the margin, so Indian refiners pay peak rates during disruptions. Owned or long-term chartered tonnage converts that volatility into a fixed cost — the shipping equivalent of an option premium.
Storage: A Crude Cushion, an LPG Gap
Sahney also called for investment in crude and LPG storage to give the country a few more days of cushion, and the data supports him on both counts.
India’s dedicated Strategic Petroleum Reserves total 5.33 million tonnes across Visakhapatnam, Mangaluru and Padur — roughly 9.5 days of crude requirement. Oil marketing companies hold a further 64.5 days of commercial inventory, taking total national coverage to about 74 days against the International Energy Agency’s 90-day benchmark. The Phase II expansion, adding 6.5 million tonnes at Chandikhol and Padur, would lift strategic capacity to about 11.8 million tonnes if completed.
LPG is the sharper vulnerability. India imports roughly 60% of its LPG, much of it from the Gulf, and holds only two underground LPG caverns with a combined 140,000 tonnes of capacity — HPCL’s Mangalore facility and South Asia LPG Company’s Visakhapatnam terminal. That is a few days of cover for a fuel used by more than 300 million households.
For the ports and terminals sector, that gap is a direct project pipeline: LPG import terminals, salt-cavern storage, cryogenic and pressurised tankage, and the pipeline links that connect them to bottling plants.
What It Means for Ship Finance
If India’s stated direction holds, the financing requirement is substantial and varied.
- Vessel acquisition. Crude carriers are long-lived, dollar-denominated assets requiring export credit, ship mortgage finance or leasing structures. Indian banks have limited appetite for cross-border shipping risk; the gap is typically filled by Korean, Japanese and European lenders.
- Charter-backed debt. Lenders will fund newbuildings against long-term charters to creditworthy refiners. The refiners’ willingness to sign multi-year commitments is therefore the gating factor, not yard capacity.
- Yard capability. Domestic shipbuilding capacity for large crude carriers is limited, which is why the policy target for Indian-built tonnage starts at such a low base. Shipbuilding finance, yard upgrades and technology partnerships sit behind any fleet ambition.
- Working capital. More owned tonnage shifts charter hire off the P&L and onto the balance sheet, changing how refiners’ freight exposure appears to analysts and rating agencies.
There is also a market-timing risk that finance teams should flag: ordering tankers at a cyclical peak in charter rates has historically led to overcapacity and weak returns when the cycle turns. A 112-vessel programme spread over 14 years is defensible; a compressed ordering spree would not be.
Frequently Asked Questions
1. What did the IOC chairman say about India’s shipping capacity?
A S Sahney said India has been “neglecting shipping” and must build its own capabilities, warning that high freight costs are eroding the benefit of discounted crude purchases. He spoke at the Energy Technology and Innovation Meet in Goa on October 27.
2. Why are freight rates so high for crude coming to India?
Freight for Russian oil exports from western ports to India hit record highs in early October, driven by heightened Black Sea security risks and a broader rally in global tanker rates, which tightened tonnage availability.
3. How dependent is India on imported crude?
India imports roughly 85–90% of its crude requirement, making it the world’s third-largest oil importer. Most of that volume is carried on foreign-flag tonnage.
4. How many days of crude and LPG storage does India have?
Dedicated strategic crude reserves of 5.33 million tonnes cover about 9.5 days, with oil marketing companies holding another 64.5 days of commercial stock — about 74 days in total against an IEA benchmark of 90. LPG cover is far thinner, with only 140,000 tonnes of underground cavern capacity against roughly 60% import dependence.
5. What would India’s fleet expansion mean for ship finance?
It would generate demand for vessel acquisition finance, charter-backed debt for newbuildings and shipbuilding investment at Indian yards, largely requiring offshore lenders given limited domestic appetite for cross-border shipping risk.
 Join our WhatsApp channel for more updates:
 Subscribe to our YouTube channel for more updates: